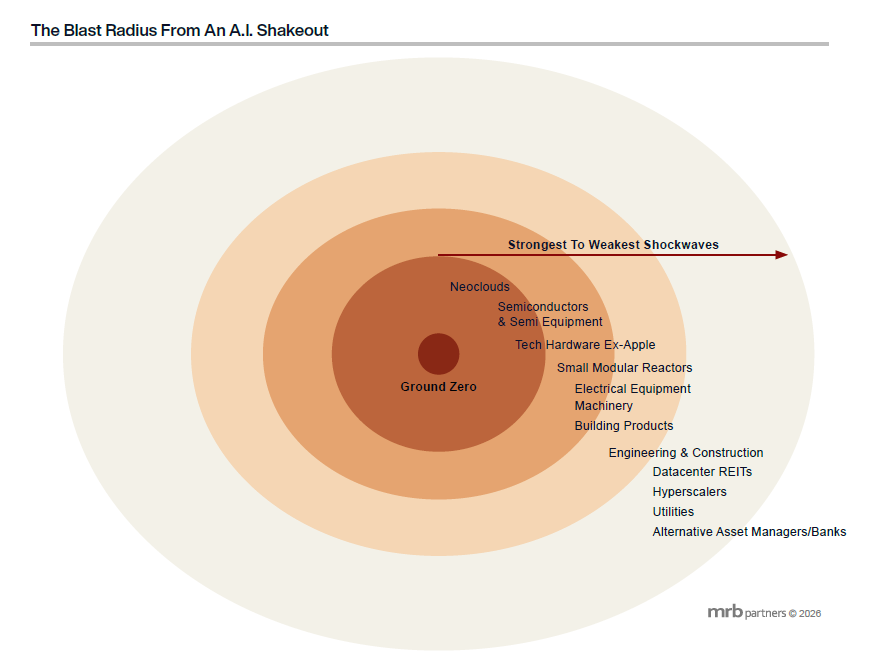
A just-published report discussed how the shocks from the budding shakeout in the A.I. investment theme might propagate throughout its various components given the circular relationships that exist within the A.I. edifice.
The A.I. value chain is comprised of three main segments: the owners/operators of the datacenters; the suppliers of the equipment inside the datacenters; and the providers of power to the facilities. The neocloud companies are the weakest link in the chain given their dependence on expensive external financing. The groups most at risk from an A.I. reckoning include the semiconductor and tech hardware & equipment industries, followed by the capital equipment companies supplying the power distribution and thermal systems to the datacenters.
Utilities are less vulnerable after this year’s sell-off in the sector, which has restored valuations to reasonable levels. And the hyperscalers and datacenter REITs should face less fallout from an A.I. setback. In the end, the ultimate impact on these groups and the private credit firms/banks financing the data infrastructure buildout will depend on the severity of the shock – stay tuned.