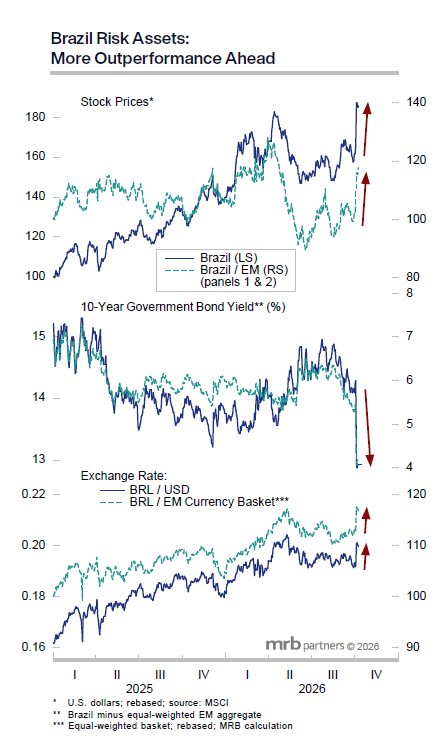
Brazil’s first round of the presidential election provided a solid boost to BRL assets last week, with a win by the right-wing candidate (Flavio Bolsonaro). As we had noted well before the election, investors were not positioned for such an outcome. Importantly, last week’s report noted that there is still plenty of capital available to buy Brazilian bonds, stocks and the currency, as investors embrace prospects for fiscal tightening and pro-growth reforms.
A Bolsonaro-led government would be expected to have better relations with the U.S. administration, implying good odds of lower U.S. tariffs on Brazilian goods (relative to current punitive rates). Moreover, prospects for increased U.S. investments and joint partnerships would be much improved under Bolsonaro. Nevertheless, he will still have to walk a fine line between accommodating Washington’s demands and protecting the domestic economy, which could occasionally unnerve investors.
Net: despite last week’s huge moves, we are still upbeat on BRL assets.